| |
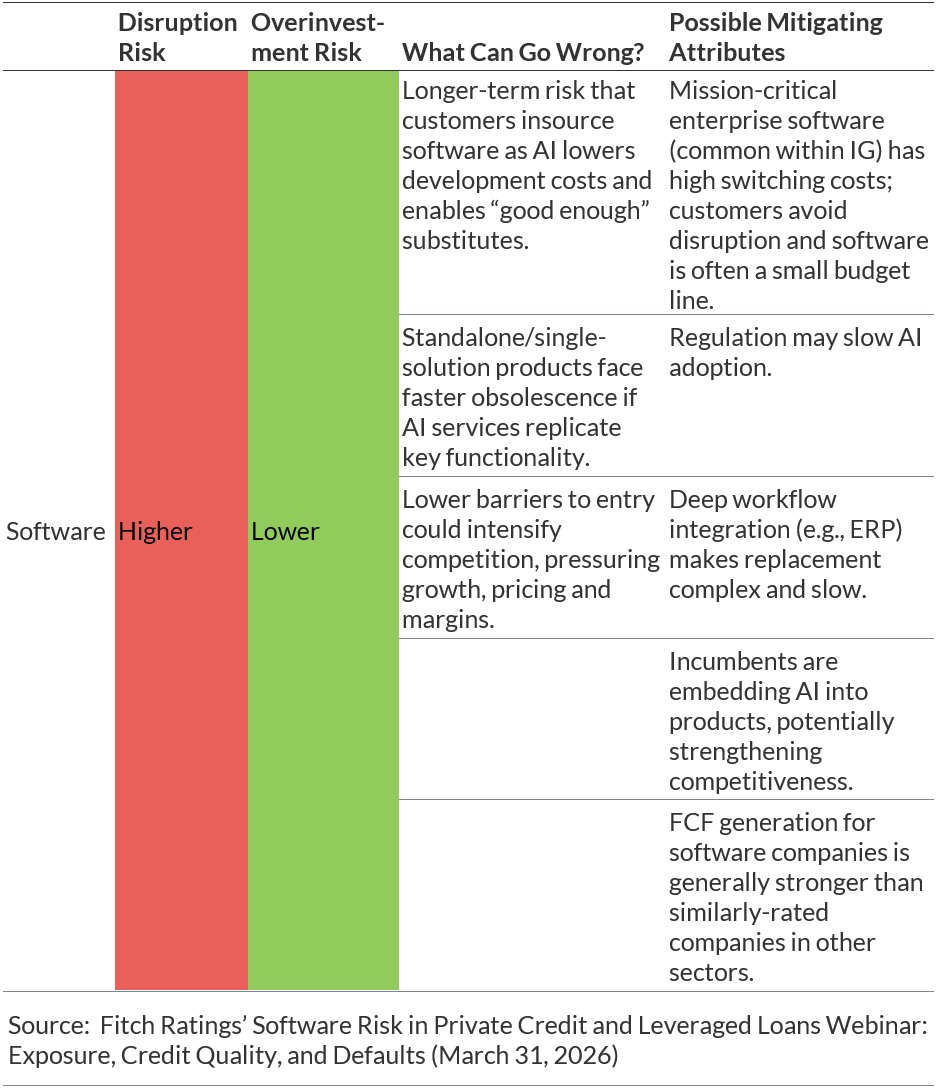
Chart of the Week: Disruption Risk in Software Companies Depends on Criticality
AI is beginning to disrupt corporate business models by reshaping cost structures, revenue models, and competitive moats. Corporate analyst Alen Lin said at a webinar last week that the software, services and media sectors appear most exposed because of their asset-light nature, where value is driven by intangibles rather than hard assets. Mission-critical product offerings are likely to be more resilient when integrated into regulation and workflows and supported by proprietary data. Lin was joined in the webinar by analysts from Non-Bank Financial Institutions, Private Credit, collateralized loan obligation (CLO) and business development company (BDC) teams, who all discussed AI’s impact in their areas.
|
|
|
|
|
|
|
|
|
|
|
|
| |
Software Risk in Private Credit and Leveraged Loans: Exposure, Credit Quality, and Defaults webinar held
The webinar covered a wide range of analytical topics, including;
- Current dynamics shaping the software sector and how to distinguish material credit signals from short‑term noise
- How software‑linked exposures across CLOs, BDCs and private credit portfolios factor into evolving risk assessments
- Where software concentration and rating sensitivities sit across AltIM and other lending platforms
- Key developments Fitch Ratings’ analysts are watching as software fundamentals and AI‑related pressures evolve
See replay here
Back to Top
|
|
|
|
| |
|
|
| |
|
|
| |
DISTRESSED DEBT AND BANKRUPTCY WATCH
|
|
|
|
| |
Lugano Diamonds & Jewelry Obtains Extension of Chapter 11 Exclusivity
Lugano Diamonds & Jewelry (Lugano) obtained a 120-day extension of its exclusivity period to file a Chapter 11 plan and solicit votes under a March 31 order. The order extends the debtor’s plan filing deadline to July 14 from March 16 and the solicitation deadline to Sept. 14 from May 15. Lugano sought the extension on March 13, citing the need for more time to continue negotiations with its secured lender and majority shareholder Compass Group Diversified Holdings (Compass) and the unsecured creditors’ committee.
The debtor stated that it had completed sale processes for substantially all of its assets to Enhanced Retail Funding, an affiliate of Gordon Brothers, which also entered into an agency agreement to liquidate Lugano’s inventory and other assets. Lugano filed for Chapter 11 on Nov. 16, 2025, with USD678.4 million owed to Compass under a secured credit agreement that included a term loan and revolver components. The bankruptcy filing followed Compass’s mid-2024 investigation into Lugano’s financing, accounting, and inventory, and subsequent allegations that the former CEO forged invoices, disguised financing deals as sales, concealed payment obligations, mailed empty-box shipments, and misrecorded third-party funds as revenue.
Multi-Color Corp. Receives Final DIP Approval with Revised Terms
Multi-Color Corp. reached a revised agreement with the ad hoc secured lender group providing its debtor-in-possession (DIP) financing after Judge Michael Kaplan said he would approve the company’s USD657.5 million DIP facility on a final basis. However, he said he would not approve the full proposed roll-up outside of plan confirmation or a broader settlement. Under the revised deal, Multi-Color Corp. will have access to USD125 million, consisting of a USD62.5 million roll-up and USD62.5 million new money, with the remaining roll-up issue to be revisited at a plan confirmation hearing scheduled for April 13.
The company had originally proposed a DIP package with USD400 million of new money, a USD250 million roll-up of prepetition first-lien debt and a USD7.5 million backstop premium, but the financing and related restructuring support agreement have faced opposition from an ad hoc cross-holder group pushing an alternative DIP without a roll-up. Multi-Color Corp. has argued that the rival proposal does not provide a viable restructuring path, while the lender-backed plan tied to the DIP could eliminate USD3.9 billion of its USD5.9 billion in funded debt. The company originally filed for Chapter 11 on Jan. 29 with support from its ad hoc secured lender group and equity owner Clayton Dubilier & Rice due to operational and macroeconomic pressures.
Back to Top
|
|
|
|
| |
|
|
| |
|
|
| |
RATING CHANGES AND SECONDARY MARKET MOVES
|
|
|
|
| |
This section highlights notable recent price movements among issuers and indices in the U.S. bond and loan markets, based on changes in closing bids through Friday, April 3.
- The average high-yield (HY) spread over U.S. Treasuries decreased to 316 basis points (bps) on Wednesday, April 1, down from 317 bps the previous week, according to Intercontinental Exchange Bank of America.
- The average bid for first-lien institutional leveraged loans was 94.90 as of April 2, according to CreditSights.
Fitch Upgrades Sandisk's LT IDR to 'BB+'; Outlook Stable
Fitch has upgraded Sandisk Corporation's Long-Term Issuer Default Rating (IDR) to 'BB+' from 'BB'. Fitch has also affirmed Sandisk's 1st-lien senior secured debt at 'BBB-' with a Recovery Rating of 'RR1'. The Rating Outlook is Stable.
The ratings and Outlook reflect Sandisk's debt reduction with available cash, achieving its net cash target ahead of schedule and providing the company with ample flexibility to invest in growth through the cycle. Flash memory markets will remain cyclical, but operating performance for Sandisk and the industry more broadly will be strong for at least the next two years due to robust spending onAI infrastructure.
The Rating Watch reflects the expected reduction in leverage from the sale proceeds of the WNBA basketball team, Connecticut Sun. The potential application of most of the proceeds to debt reduction could result in a positive rating action.
The rating also reflects the leading market position of the Mohegan Sun casino, growing digital results, and positive FCF generation, as well as a lack of geographic diversification, the potential impact of the opening of New York City casinos and limited financial flexibility.
Back to Top
|
|
|
|
| |
|
|
| |
|
|
| |
ISSUANCE AND FUND FLOWS MONITOR
|
|
|
|
| |
Broadly Syndicated Loans
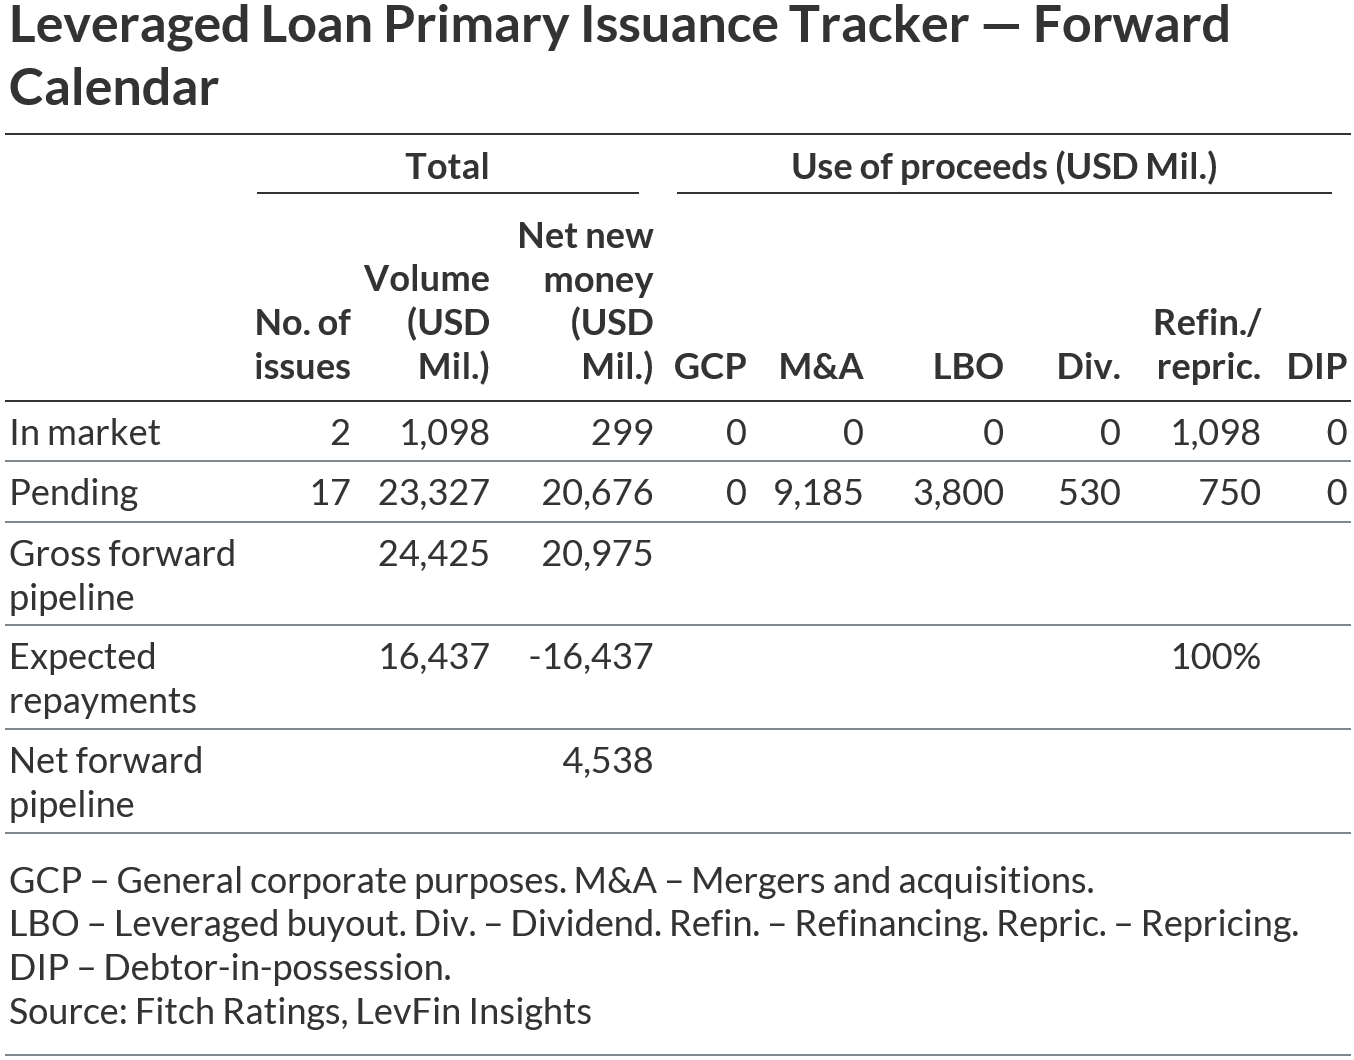
Sealed Air dominated the week's loan activity as CD&R's USD10.3 billion take-private financing was reworked materially before pricing. The company completed an approximately USD3.5 billion seven-year dollar term loan at S+400 with a 95 Original Issue Discount (OID), downsized from the originally marketed USD4.1 billion as roughly USD500 million shifted to secured bonds and approximately USD150 million shifted to the euro tranche, which increased to EUR650 million. CD&R is contributing approximately USD3.1 billion of equity, or roughly 29% of total capitalization. The transaction went through multiple rounds of documentation revisions before clearing, including the removal of a provision allowing the issuer to spin off a business line, according to LevFin Insights (LFI).
Other notable new-money transactions included Venture Global Calcasieu Pass, which is in the market for a USD1.75 billion seven-year term loan, being marketed at S+325 with a 98.5 OID, tightened from initial guidance of S+350-375. Proceeds will fully repay Stonepeak's redeemable preferred equity investment. The loan includes a 1.1x debt service coverage ratio. CPV Three Rivers completed a USD750 million term loan at S+275 with a 99.5 OID to refinance approximately USD603 million of bank debt and fund a shareholder dividend. Two Kings Casino completed a USD345 million add-on term loan at S+475 at par to fund expansion financing.
Refinancing activity was also notable. Grifols completed an upsized cross-border refinancing consisting of a USD2.0 billion dollar term loan and a EUR1.25 billion euro term loan, both increased from launch minimums. The dollar tranche priced at S+250 with a 99.25 OID. Proceeds will redeem EUR740 million of 2.25% secured notes due 2027, refinance euro and dollar term loans due 2027, and add cash to the balance sheet. Mativ Holdings completed a USD500 million refinancing term loan at S+450 with a 95 OID after widening from initial guidance of S+425 at 98-98.5 and revising documentation, notably removing the ability to refinance unsecured bonds with secured debt, according to LFI.
SK Capital-owned Archroma launched an approximately USD846 million equivalent cross-border first-lien refinancing due 2030, including at least USD200 million in dollars, alongside a USD200 million second-lien tranche due 2030. The first-lien debt is marketed at E/S+500-525 with a 99 OID and a 1% exit fee, while the second-lien is guided at S+900-925 with a 97 OID.
|
|
|
|
|
|
| |
Private Credit
March continued February’s momentum, setting a record for private debt issuance volume. LFI captured USD41.13 billion in private debt issuance year-to-date (YTD) and USD13.27 billion month-to-date through March 27th. Both are records for March and March YTD since LFI began tracking private debt issuance in 2015. LBOs and M&A drove private debt issuance in March, including Thoma Bravo’s USD4.81 billion LBO of WWEX Group, Paratek and Radius Health’s USD1.3 billion merger, and Clearlake’s USD900 million LBO of Qualus Corporation.
Jushi Holdings (Jushi) received a USD160 million term loan from FocusGrowth Asset Management to refinance its first and second-lien term loans. Part of the debt refinanced will be a USD48.5 million term loan issued in July 2024. The refinancing was to address Jushi’s September 2026 maturity. The upcoming maturity triggered a ’substantial-doubt’ warning in their 3Q25 quarterly report. Jushi operates 42 cannabis retail locations as well as cultivation and manufacturing facilities.
Mesabi Metallics (Mesabi) was given a USD520 million senior credit facility from Breakwall Capital. The proceeds from the senior credit facility will be used to commercialize operations later this year. Mesabi is creating a merchant direct reduction-grade iron ore mine and pellet plant, the first new mine and pellet plant in Minnesota in almost 50 years.
Back to Top
|
|
|
|
| |
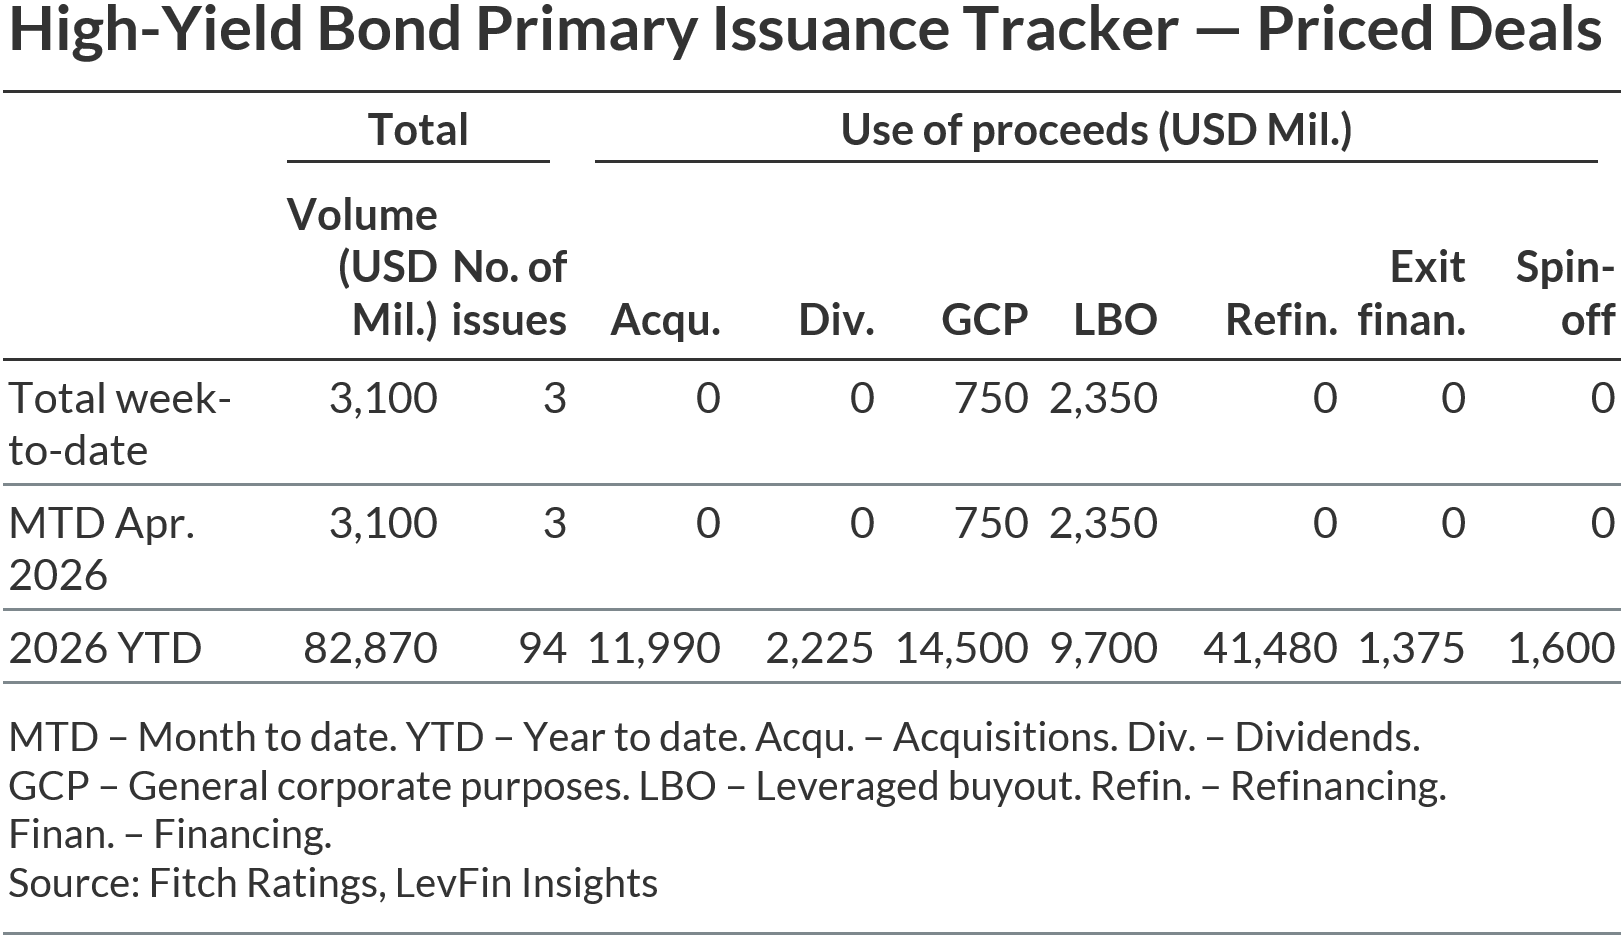
HY Bond Issuance
Sealed Air also led bond issuance, completing the note portion of its CD&R take-private financing with the dollar secured tranche upsized to USD1.85 billion from the originally marketed USD1.35 billion as demand shifted from the term loan. The broader package included euro-denominated secured notes and USD500 million of senior unsecured notes due 2034. Proceeds support the acquisition and refinancing of existing debt. The existing USD458 million 6.875% 2033 notes will remain outstanding and become secured at close, while other unsecured notes will be called.
Skeena Resources, a precious metals developer advancing the Eskay Creek gold-silver project in British Columbia, completed a USD750 million debut first-lien notes offering due 2031 at 8.5%, inside early talk in the 8.75% area and at the tight end of revised guidance of 8.5%-8.625%. The five-year NC2 notes will fund the buydown of a streaming agreement, a disbursement account to advance construction at Eskay Creek and an interest reserve account sized to cover interest through the third semiannual payment date. The deal was reportedly well oversubscribed, according to LFI.
Beyond those two transactions, the primary high-yield calendar was limited for the week, with broader issuance constrained by macro volatility and the holiday weekend.
Back to Top
|
|
|
|
|
|
| |
|
|
| |
|
|
| |
FUND FLOWS AND CLO ISSUANCE
|
|
|
|
| |
For the tenth consecutive week, retail loan fund flows remained negative, with USD145 million in outflows for the week ended April 1. This figure is a slight increase from the USD178 million in outflows recorded during the previous week. The current streak of outflows has totaled USD6.67 billion. YTD net outflows total USD5.7 billion, compared with USD1.9 billion in inflows over the same period in 2025.
HY retail funds remained negative for the eighth consecutive week, with USD2.55 billion in outflows for the week ended April 1. This week’s outflow figure is deeper than the USD1.97 billion in outflows recorded during the previous week. At eight weeks, the current streak of outflows for HY retail funds is the longest streak since 1Q22, when a streak of eleven weeks of outflows was recorded. YTD net outflows total USD11.08 billion, compared with USD7.52 billion in inflows over the same period in 2025.
For the week ended April 3, one new BSL CLO was priced with a Triple-A spread of S+124 bps, and no new middle-market (MM) CLO was priced. During the same week, seven BSL CLO reset-and-refinancing deals were priced with a Triple-A average spread of S+126 bps, while one MM CLO reset-and-refinancing deal was priced with a Triple-A spread of S+155 bps. No CLO static transaction was completed during the week.
YTD, the market has priced 191 BSL CLOs, totaling USD85.7 billion. This represents a 32.7% decrease in volume year-over-year (yoy). The market has also priced 31 MM CLOs YTD, totaling USD14.8 billion, marking a 42.1% decrease in volume yoy.
Back to Top
|
|
|
|
|
|
|
|
|
|
| |
Contact Us
Lyle Margolis
Head of North America Private Credit
+1 646 582 3589
|
|
|
|
|